Microeconomics Unit 1: Demand, Supply, and Market Equilibrium, BBA (FIA) Semester 1 and BMS Semester 2
Microeconomics studies the economic decisions of individual consumers, producers, and firms. It explains how prices are determined, how consumers distribute their income, how businesses choose production levels, and how different market structures influence competition and economic welfare.
The syllabus is divided into four major units:
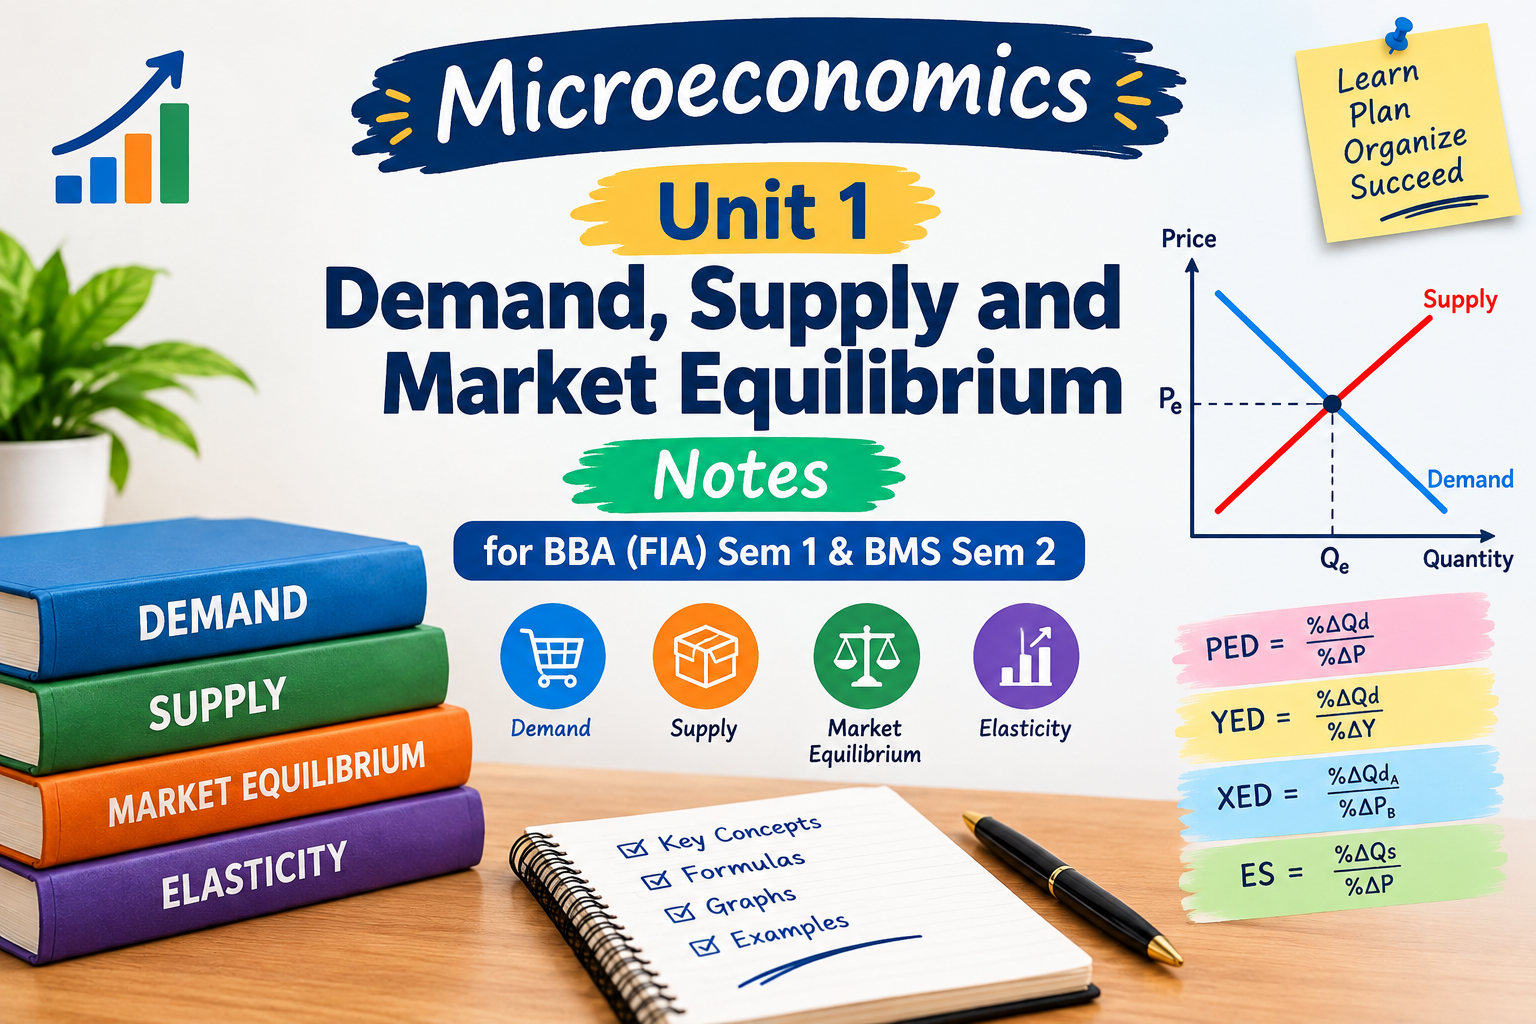
- Unit 1: Demand, Supply, and Market Equilibrium
2. Unit 2: Theory of Consumer Behavior
3. Unit 3: Producer Behavior and Optimal Production Choice
4. Unit 4: Market Structures
Unit 1: Demand, Supply, and Market Equilibrium
1.1 Introduction to Demand
Demand refers to the quantity of a product that a consumer is willing and able to purchase at different prices during a particular period, assuming other influencing factors remain unchanged.
1.1.1 Individual Demand
Individual demand describes the purchasing behavior of a single consumer. It indicates how many units of a product that person intends to buy at different prices.
For example, a student may purchase five cups of coffee per week when the price is ₹20 per cup but reduce consumption to three cups when the price rises to ₹30.
1.1.2 Law of Demand
The law of demand states that, other things remaining constant, a rise in price generally reduces quantity demanded, while a fall in price increases quantity demanded.
Main Features of the Law of Demand
– Price and quantity demanded usually move in opposite directions.
In economic diagrams, the demand curve normally declines as quantity increases along the horizontal axis.
– The law assumes that income, preferences, related-product prices, and other relevant conditions remain unchanged.
1.1.2.1 Exceptions to the Law of Demand
Certain unusual situations may produce an upward-sloping demand relationship. Examples include Giffen goods under specific economic conditions and cases involving strong expectations of future price increases. These situations do not invalidate the general principle of demand.
1.2 Market Demand
Market demand is the combined quantity of a product that all consumers in a market are willing and able to purchase at different prices during a specified period.
1.2.1 Derivation of Market Demand
Market demand is calculated by adding individual consumers’ quantities demanded at each price. This process is called horizontal summation.
For example, if Consumer A demands 10 cups of coffee and Consumer B demands 15 cups at ₹20 per cup, total market demand equals 25 cups at that price.
1.2.2 Factors Affecting Demand
Demand may change because of:
– Consumer income and purchasing power.
– Prices of substitutes and complementary goods.
– Consumer preferences, fashion, and advertising.
– Population size and the number of buyers.
– Expectations about future prices and income.
A change in the product’s own price causes movement along the demand curve, whereas changes in other demand determinants generally shift the entire curve.
1.3 Individual Supply
Individual supply represents the quantity of a product that a single producer is willing and able to sell at different prices during a given period.
1.3.1 Law of Supply
The law of supply states that, other things remaining constant, producers generally offer larger quantities for sale when prices rise and smaller quantities when prices fall.
1.3.1.1 Supply Curve
The supply curve normally slopes upward because higher prices can make additional production more profitable, encouraging firms to increase output.
For example, a sandwich seller may be willing to supply 20 sandwiches daily at ₹50 each but increase the quantity offered to 30 sandwiches when the price rises to ₹70, assuming costs and other conditions remain unchanged.
1.4 Market Supply
Market supply is the total quantity of a product that all producers in an industry are willing and able to sell at alternative prices.
1.4.1 Calculation of Market Supply
Market supply is obtained by adding the quantities supplied by individual firms at each price.
For instance, if Firm A supplies 50 units and Firm B supplies 70 units at ₹100 per unit, market supply equals 120 units at that price.
1.4.1.1 Factors Influencing Supply
Supply depends on production costs, technology, taxation, subsidies, the number of producers, input availability, and expectations regarding future market conditions.
1.5 Market Equilibrium
Market equilibrium occurs when the quantity buyers wish to purchase equals the quantity sellers wish to sell at the prevailing price.
1.5.1 Equilibrium Price and Quantity
Equilibrium Price (Pe): The price at which the quantity buyers are willing to buy equals the quantity sellers are willing to offer.
– Equilibrium quantity (Qe): The quantity exchanged at the equilibrium price.
1.5.1.1 Numerical Illustration
| Price of Goods | Consumer Purchase Quantity | Producer Sales Quantity |
| ₹20 | 100 | 20 |
| ₹40 | 80 | 40 |
| ₹60 | 60 | 60 |
| ₹80 | 40 | 80 |
| ₹100 | 20 | 100 |
At ₹60, buyers demand 60 units and producers supply 60 units. Therefore, the equilibrium price is ₹60, and the equilibrium quantity is 60 units.
1.5.2 Shortage and Surplus
Surplus exists when supply exceeds demand at a given price. Sellers may respond by lowering prices.
At a given market price, a shortage exists when the quantity consumers want to buy is greater than the quantity producers are prepared to supply. Competition among buyers can put upward pressure on prices.
1.5.2.1 Changes in Equilibrium
– When consumers demand more of a product, the equilibrium price and quantity generally increase.
– A decrease in demand generally lowers equilibrium price and quantity.
– When producers supply more of a product, the equilibrium price generally declines while the quantity exchanged increases.
– A decrease in supply generally raises equilibrium price and lowers equilibrium quantity.
These outcomes assume that the other curve remains unchanged.
1.6 Elasticity of Demand and Supply
Elasticity measures the responsiveness of quantity demanded or supplied to changes in price, income, or the prices of related products.
1.6.1 Price Elasticity of Demand (PED)
Price elasticity of demand measures the percentage change in quantity demanded resulting from a percentage change in price.
1.6.1.1 Formula and Interpretation
$$
PED=\frac{\%\Delta Q_d}{\%\Delta P}
$$
Price elasticity of demand is generally below zero because a price increase normally causes quantity demanded to fall. Its absolute value is used to identify the type of demand elasticity.
– Elastic demand: $|PED|>1$
– Inelastic demand: $|PED|1$
– Inelastic supply: $ES<1$
– Unitary elastic supply: $ES=1$
If the price rises by 10% and the quantity supplied increases by 20%, the elasticity of supply equals 2. Supply is elastic because output responds proportionately more than price.
Conclusion
In conclusion, microeconomics helps us understand how consumers and producers make economic decisions and how prices are determined in a market. Unit 1 explains the fundamental concepts of demand, supply, market equilibrium, and elasticity, which influence the buying and selling of goods and services. It also shows how changes in prices, income, consumer preferences, production costs, and market conditions affect market outcomes. Understanding these concepts provides a strong foundation for studying consumer behavior, production decisions, and different market structures in the subsequent units of microeconomics.
Also Read: Unit 2: Theory of Consumer Behavior
Frequently Asked Questions (FAQs)
1. What is microeconomics?
Microeconomics is the branch of economics that studies the decisions of individual consumers, producers, and firms, including pricing, production, consumption, and resource allocation.
2. What is the law of demand?
The law of demand states that, other things remaining constant, quantity demanded generally decreases when price rises and increases when price falls.
3. What is the difference between cardinal and ordinal utility?
Cardinal utility theory assumes that satisfaction can be measured numerically, whereas ordinal utility theory explains how consumers rank different combinations of goods according to their preferences.
4. What are the four major market structures?
The four major market structures are perfect competition, monopoly, monopolistic competition, and oligopoly. They differ in the number of firms, product differentiation, barriers to entry, and degree of control over prices.